≡ Menu

I, Robot

I, Robot post image

There is nothing like investing when it comes to exposing yourself as a weak-minded gimboid.

I know all about buying stocks low and selling high. I understand the rationale behind Warren Buffett’s aphorism, “be fearful when others are greedy and greedy when others are fearful.”

Yet when my portfolio hits red, I fret. And when my return numbers glow green, I feel the pleasure centres in my brain light up like Vegas.

The uptick in fortune means it will cost me more every time I buy additional equities, of course. But hang the expense, I want to be a part of this now! The party’s on and I need to get my snout in the trough, quick.

I know this because despite being a good passive investor who pound-cost averages and rebalances annually, I am not an entirely mechanical man.

And oh, the flesh is weak.

Only flesh and blood

You see I long allowed myself a measure of freedom when investing – a certain amount of money to put into the market every year that wasn’t dictated by the calendar.

Don’t get me wrong. This was never a gambler’s float, used to punt on some company that’s rumoured to be on the verge of discovering cancer-curing jam.

I invested my discretionary dollop in index trackers. However I was free to do so whenever I wished.

Sounds good? The snag is that in reality I struggled to take the plunge when the market did. I wasn’t always been brave enough to blow my ammo when equities were relatively cheap. I held on and on until the upswings, and then I got less for my money.

Oh I had my excuses. Especially when I hadn’t yet escaped the rat race, and so was still subject to the whims of The Man as well as Mr Market.

Impure instinct

Especially before full-strength financial independence had my back, my brain was always on hand with self-justifications to reassure me that reason was actually in control, not instinct:

  • I was worried about my job.
  • My company was restructuring.
  • My monthly drip-feed was already casting cash into the cavernous cake hole of the capital markets.
  • “I better not throw in any more in case I’m axed! I’ll need every penny.”

The reality was that the overweening fear of loss was in charge.

What these optional investing side quests actually taught me was I am just one of the herd. A member of the cattle class.

I’m not special. I react and feel like everyone else who makes up the statistics that show this sort of irrational behaviour can cost investors dear.

Gorilla warfare

The truth is it takes willpower to overcome the apeman within, and there’s some evidence that willpower is in limited supply for all of us. We can’t bank on having enough in reserve when we need it.

This in turn means the fewer decisions that are left up to my meat-bag of a brain, the better.

Passive investing would be much easier if we could program a robot to handle it all for us and to physically prevent our continued interference, like some benevolent Dalek with a taser.

Perhaps the AI revolution will give us all the cold-blooded reptilian investing agent of our dreams?

Once it’s emerged from the primordial slop, I mean.

Well, perhaps. But until we can trust an agent to run our portfolio without it going rogue and selling the house to bet everything on pork futures, it’s up to us to manage our all-too-fallible frontal lobes.

Don’t just do something

Back when I still stacking my escape-stash, automatic investing droids were nowhere to be seen. So instead I automated as much of the investing process as possible.

You see, the one human behaviour that always worked for me is inertia.

  • I never messed with the direct debit that funnelled money out of my bank account and into my broker’s.
  • I kept hands-off the regular investment scheme that piped cash straight to my chosen funds.
  • I dared not touch lock-in wrappers like ISAs, pensions, and fixed-term bank accounts, where a cost is imposed for premature evacuation.

Inertia is the great human pacifier. It’s a force that’s more powerful than fear in my world – especially if the fear is something intangible, like an investing loss.

Eliminate all carbon units

There are other weak points where human intervention can easily scupper the best plans.

For instance, you might fiddle with asset allocation every time you choose the next fund to buy. And, boy, what mischief you can get up to when it’s time to rebalance…

“Sell those lovely equities to buy more bloody bonds. In this market?!”

Putting my investing on rails did help me to resist the urge to keep thrashing my winners.

But it sometimes also took a stiffening of resolve, and a quick prayer of deliverance to the passive investing gods.

Older and colder

Since I declared myself FIRE – and declared to my bosses where they could shove The Accumulator’s Personal Growth and Development Plan V4.6 – I’ve found it easier to leave my portfolio to do its thing.

I suppose the same fully-funded sangfroid that enables me to do some work on the side without getting sucked back into the office is also helping me to ignore the market noise.

Have I then reached some state of investing transcendence?

Doubtful. So far so good, but I’m regularly tested and I’m still only a passive investor.

I stayed the course during the Covid crash, true, and I learned more than I lamented during the recent bond-a-geddon.

But who knows how a real humdinger of a bear market would hit me?

Better to stay humble and self-aware.

Automatic for the people

If you recognise these frailties in yourself, then there are various tools you could explore to take the human edge off – from automatic investment plans at online brokers, to all-in-one personal finance apps that limit your investing choices but also your horizons.

They can still be enablers when it comes to self-destructive fiddling, though. And they can be relatively expensive.

These days there’s a lot of talk that AI agents will soon do everything for us. In theory it sounds like automatic investing nirvana. But when you think about how obsequious the typical chatbot is, would you really trust one not to egg on your worst impulses?

Besides, from what I can see AI is so far mostly being deployed to tempt investors off the rational path.

All-in-one not one-for-all

Perhaps the closest proxy for a truly hands-off investing robot is a good multi-asset fund.

Made popular in the UK by Vanguard’s LifeStrategy products, a multi-asset fund is an index-tracking, fund-of-funds with built-in rebalancing features – truly automatic investing.

All you need do is pick the asset allocation of your choice, set-up a direct debit to keep it oiled, and then let the program run.

With this sort of investing the human being is taken off the table – which is the point of the exercise after all – and everything is left to the robot. No more pesky emotions.

Of course, you might eventually start to worry that your multi-asset fund hasn’t got all the assets you want. Not in the right doses, anyway.

Perhaps you’re being greedy or fearful, or perhaps you’ve become better informed. Humans are not incapable of judgement, after all. It’s the rash decisions we want to tamp down, not the strategic thinking.

At least with your investing machine whirring away in the background, you can take time to explore your options with the serenity of a wannabe Cyborg Buffett.

Batteries not included.

Take it steady,

The Accumulator
{ 32 comments }

Weekend reading: Who wants to see a billionaire?

Weekend Reading logo

What caught my eye this week.

I am sure you’ve noticed. The absence of the once-familiar chop of helicopters overhead. No longer being cut up by Ferraris and Lambos on the M1. It suddenly being easy to find unwanted copies of Atlas Shrugged at your local library.

Weekend Reading – featuring the week’s best money and investing articles from around the web – can be read by any logged-in Monevator member. Alternatively please subscribe to our free email newsletter to get future editions direct to your inbox.

{ 8 comments }

This is a guest article by Sam Parkinson, the creator of Pension Sprout.

A recent Monevator piece about Gen Z and pensions quoted a young reader stating flatly: “I don’t believe that I’ll be a recipient of a State Pension.”

I’ve read a lot of responses to that sort of line. Mostly they’re some variation of “don’t worry, it’ll be fine”, which is unconvincing and slightly patronising because nobody actually knows the future.

Indeed while the recently-mooted shake-up of the State Pension’s triple-lock from 2030 is pitched as making it more sustainable for the long run, some people will instead see it as proof that politicians will always be tempted to tinker it away, or at least introduce means-testing for what’s now a universal benefit.

So let’s take concerns about the future of the State Pension seriously. Because if you genuinely think the State Pension won’t be there for you, the useful question is what your alternative plan will cost you if you’re proven right. Work that out and you’ll find out what you’re really arguing about.

I run a free pension calculator, which is how I ended up doing this arithmetic in the first place.

Be warned: the number is bracing!

What you’d replace with a DIY State Pension

For the purposes of this article we’ll assume the pension triple-lock continues in its existing form. We don’t know who’ll be governing the UK in 2030 – and thus we can’t be sure if and how the triple-lock will change. Modest tweaks don’t alter the central premise, anyway.

The full new State Pension is currently £241.30 a week for 2026/27, or £12,547.60 a year (Source: GOV.UK). Call it £12,548.

We should focus on the State Pension’s specification rather than that number, though, because the specification is the expensive part:

  • The State Pension is paid for life, however long you live.
  • It is currently uprated every year under the triple lock, by the highest of earnings growth, CPI, or 2.5% (Source: House of Commons Library).
  • You’re not relying on an insurer or an investment fund to deliver the income.
  • It isn’t means-tested.

If a private company sold this as a product, it would be the most conservative one on the shelf.

The market price

The nearest alternative to the State Pension you can buy is an RPI-linked annuity.

Hargreaves Lansdown publishes best buy rates. As at 17 September 2026, a single-life RPI-linked annuity with a five-year guarantee paid £5,566 a year per £100,000 at age 65. 1

Hargreaves Lansdown doesn’t quote for age 68 – the State Pension age a 25-year-old is currently legislated to reach. Its table runs 65 then 70, at £5,566 and £6,338 respectively.

However interpolating those two numbers gives us roughly £6,029 per £100,000 at 68. (That’s my arithmetic, not a quote, so treat it as indicative.)

  • Divide £12,548 by 6.03% and you get £208,000.

Thus £208,000 is what it costs, today, to buy the income the State Pension gives you, at the age you’d get it.

Note that a few weeks earlier the same table showed £5,585 at 65. The rate moved by around a percentage point over that short period, and the replacement cost by thousands of pounds with it. So please do take every number in this section as just a snapshot of one week’s pricing.

For more context, replacing the same income three years earlier at age 65 would cost about £225,000.

Or – if you’d settle for a level annuity that never rises – £156,000.

That last figure is the one people quote when they want the State Pension to look cheap. But it’s not a fair comparison, because inflation will eat a level annuity alive over a 25 year retirement.

And £208,000 is a low-ball estimate…

An RPI-linked annuity tracks RPI. But the State Pension currently tracks the triple lock, which is the highest of the three measures cited above. The State Pension has therefore generally run ahead of prices since the triple lock was introduced.

The Commons Library notes that the basic State Pension’s value relative to average earnings climbed from around 16% in the 2000s to roughly 26% under the triple lock. So an annuity that merely keeps pace with RPI is a worse product than the thing it’s replacing.

Also, RPI itself is changing.

From February 2030, RPI will be aligned with CPIH, which has historically run about a percentage point lower. Anyone buying an RPI-linked annuity today is therefore buying an index that is scheduled to become less generous within four years.

I suggest then it’s best we treat £208,000 as a floor.

What this all means if you’re 25

Here’s where the analysis gets more cheerful.

That £208,000 – in today’s money, 43 years away – is not an unthinkable number. You can achieve it through a monthly direct debit, wise investing, and a lot of patience.

How much your direct debit – your contribution – needs to be depends on what you assume about returns:

Real return (i.e. after inflation) Monthly saving needed from 25
2.9% a year (FCA prescribed central rate) £205
4% a year (my calculator’s cautious setting) £155
5% a year (moderate) £119
6% a year (optimistic) £90

That’s a spread of more than two to one – from £90 to £205 – in terms of how much you’ll need to put away each month, just from changing the growth assumptions.

It’s an open question as to what the most accurate figure is to use. Anyone giving you a single number is probably trying to sell you something!

Many happy returns?

It’s worth saying where the return assumptions in my table above sit compared to the regulator’s:

  • The FCA makes providers project pensions at 2%, 5% and 8% a year, with inflation assumed at 2%.

  • That is roughly 0%, 2.9% and 5.9%, after inflation.

  • My calculator’s ‘cautious’ 4% therefore sits above the regulator’s central case, and its ‘optimistic’ 6% sits above the regulator’s top one.

I’d rather be upfront about this here than have it pointed out in the comments.

Again, please read the three settings as a range to think about, not a forecast.

Tomorrow’s DIY pensioner today

Let’s now consider a 25-year-old on £39,000 (the ONS median for full-time employees in April 2025) who pays the auto-enrolment minimum of 8%, and who retires at 68.

Firstly a few things about how my tool turns the resultant pension pot into an income:

  • The calculator assumes that you take the full 25% tax-free lump sum at retirement and then draw 4% a year from what’s left.
  • The resultant retirement income figure includes a full State Pension.
  • Everything is in today’s money.
  • The tax-free lump sum sits outside this income figure, so it would be money on top.

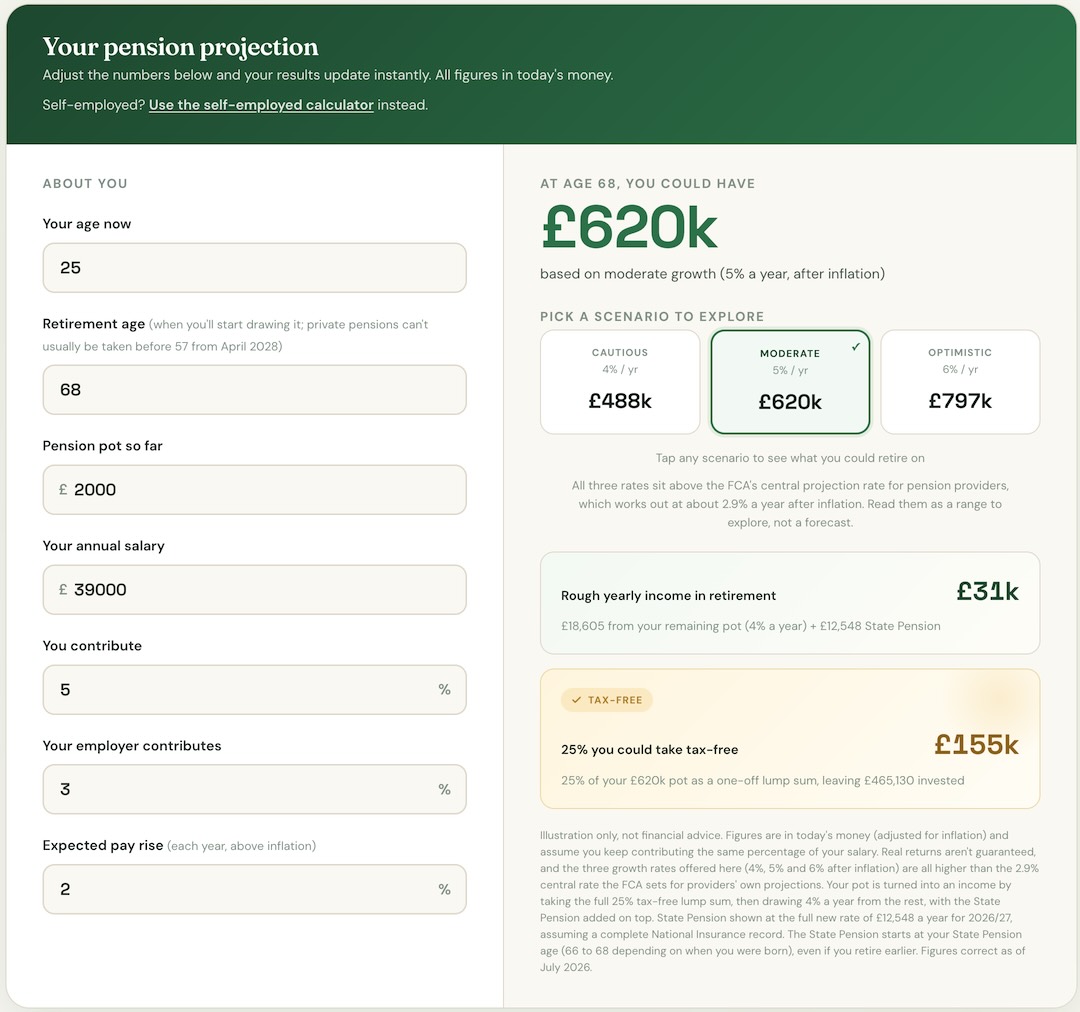
Here’s the money shot:

Source: Pension Sprout

A pot of £620,000 could produce a retirement income of about £31,000 a year. Of this income, £12,548 – roughly 40% – is the State Pension.

That £31,000 is the number I’d put in front of anyone who thinks the State Pension is irrelevant to them. On this central case, it makes up two-fifths of their retirement income. Moreover it’s two-fifths that’s inflation-proofed and can’t run out.

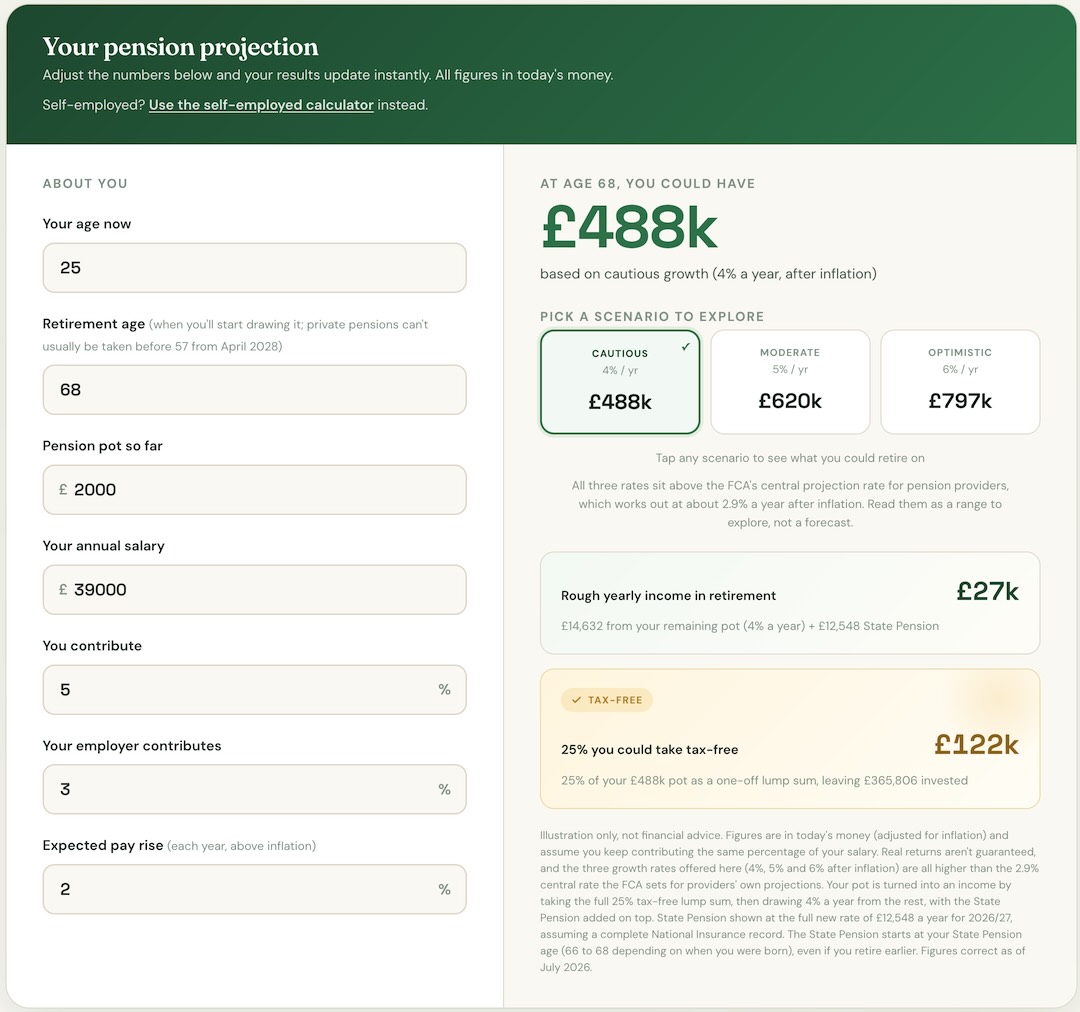
Switch the same person to the cautious 4% setting and the pot falls to £488,000:

Source: Pension Sprout

We haven’t changed the contributions, but the final sum used to buy an income is £132,000 smaller due to lower investment growth. The State Pension share of our pensioner’s resultant income climbs to 46%.

What if our 25-year-old wants to self-fund the whole thing, so that losing the State Pension entirely wouldn’t change their retirement income?

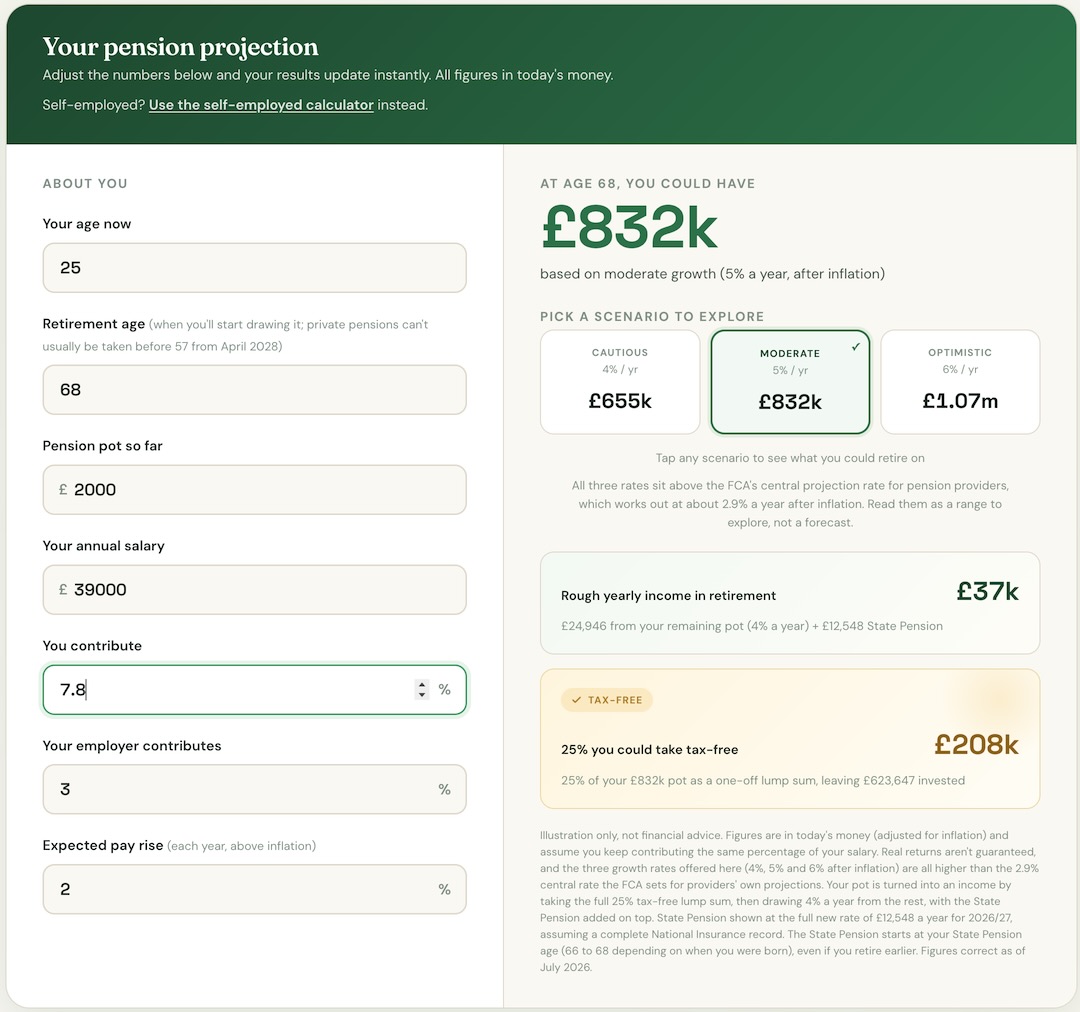
In this case they will need to lift their own contribution from 5% to about 7.8%, which takes the total from 8% to 10.8%:

Source: Pension Sprout

The higher contributions add about £212,000 to the final pot in this forecast, which covers the £208,000 extra the market would charge. It would cost around £90 a month at today’s salary, rising with pay.

I think that’s manageable beginning at age 25. (It’s brutal if you’re starting at 55 – which is a whole other lesson!)

Buying into what the government is selling

Now we get to the comparison that made me want to write this article.

You can buy extra State Pension. A year of voluntary Class 3 National Insurance costs £18.40 a week, or £956.80 for a full year. For someone who needs 35 qualifying years for the full new State Pension, one additional year adds 1/35th of the full rate.

So £241.30 ÷ 35 = £6.89 a week, or £358.50 a year, index-linked by the triple lock, for life.

Work out the implied rate:

  • £358.50 of annual income for £956.80 of capital is 37.5%. That is, it pays for itself in two years and eight months.

The open market offers around 6% on the equivalent product, whereas the state charges a price that implies about 37%.

We can push this further. If you could buy all 35 qualifying years at the price of voluntary contributions (spoiler: you can’t!) then it would cost just £33,488. The annuity market will charge you around £208,000 for the same income.

On this crude but illustrative comparison, the State Pension is available at roughly a sixth of what it’s worth, which is a strange thing to describe as the benefit nobody expects to receive.

But before anyone rushes off to their online banking, some important caveats:

  • You cannot buy 35 years of State Pension. You can normally only fill gaps in the last six tax years. And only years that aren’t already qualifying.

  • Paying doesn’t always increase your pension, particularly for anyone with a pre-2016 record or a history of being contracted out.

  • Check with the Future Pension Centre before doing anything. These payments are an easy way to waste a four-figure sum on a pension decision.

My comparison is just made to show you again what the State Pension is really worth.

So is the Gen Z reader wrong?

Not exactly, but I’d argue their fear is aimed at the wrong target.

  • “The State Pension will be abolished” is a low-probability outcome. Mostly because pensioners vote.
  • “The State Pension age will keep moving” is already happening in legislation.
  • “The triple lock should get watered down” is now the stated goal of our prime minister. It’s previously been suggested by the OBR and various think tanks, too.

In my opinion then, it’s the risk of changes to the State Pension rather than it going away entirely that we might want to plan for.

So what would I say to a 25-year-old who doesn’t believe in the State Pension?

Fine. Work out your plan as though you’ll never get it. My sums suggest this will cost you about £90 a month on the central case. Or £206 if you use the regulator’s return assumptions instead of mine. You can make up your own mind and do the maths for yourself.

Suppose you’re wrong about the politics and the State Pension endures?

Then you’ll simply retire considerably richer than you planned. There are worse mistakes!

Just don’t confuse “I don’t trust it” with “it isn’t worth anything”.

For most of us the State Pension will be the largest guaranteed 2, inflation-linked income we will ever have.

That was why I built my calculator – to put the number on the screen so people can argue about it.

If you want to run these figures with your own assumptions, you’ll find it at Pension Sprout.

Sam Parkinson built Pension Sprout after failing to find a pension calculator that didn’t ask for his email address. Sam is not a financial adviser and none of the above is advice, just information for your ongoing research. Figures correct as at 17 September 2026. They will need rechecking against the current tax year whenever you read this.

  1. Note: The State Pension doesn’t come with a five-year guarantee, which is an additional useful benefit to the annuity.[↩]
  2. i.e. Government-backed.[↩]
{ 16 comments }

The Slow and Steady passive portfolio update: Q3 2026

Our in-house passive portfolio is having a distinctly average year: up 7.8% so far in 2026, or about 4.7% after inflation.

The tale is one of double-digit equity gains, dragged down by bond fund ankle weights:

Actually, the story of 2026 is the story of the portfolio’s lifetime.

The equities bloc (in the green zone below) has performed creditably to amazingly. The 13.7% annualised return of Developed World ex-UK going back well over a decade is extraordinary:

However nominal UK government bonds have almost single-handedly stolen the icing on the cake. The gilty party has lost 3% per year, leaving the Slow & Steady with a 7.6% annualised return since launch.

(Which I’m happy with, to be clear. The objective was only ever to be average.)

The Slow & Steady is Monevator’s model passive investing portfolio. It was set up at the start of 2011 with £3,000. An extra £1,360 is invested every quarter into a diversified set of index funds, tilted towards equities. You can read the origin story and find all the previous passive portfolio posts in the Monevator vaults. Last quarter’s instalment can be found here.

All returns in this post are nominal GBP total returns unless otherwise stated. Subtract about 3% from the portfolio’s annualised performance figure to estimate the real return after inflation.

Too good to last

There was a plot twist in the story that led us to this chapter.

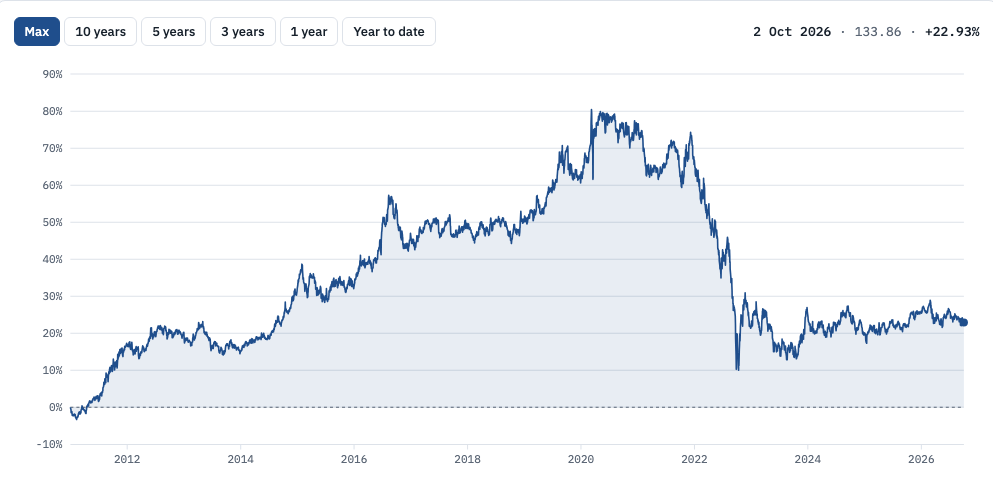
You may recall bonds had a remarkable ten-year run from 2010. But they then fell off the cliff, down 39% from the high point:

Data: Vanguard U.K. Government Bond Index Fund: 31 Dec 2010 to 02 Oct 2026.

Here’s an action-replay of the upward leg of the chart above:

Vanguard’s gilt tracker racked up 6.6% annualised returns from 2010 until its peak in March 2020.

Now for the shocker:

The same fund has dished out a -5.7% annualised loss in the six-and-a-half years since.

Bonds have recovered a little since their October 2022 trough – picking up 2.8% annualised to-date since then. Still, that’s little consolation when inflation has averaged 3.4% and World equities 13.5% in the meantime.

Are bonds broken? Is it a buying opportunity? I’ve read commentary that cuts both ways.

But…

I wouldn’t start from here

If I were starting a similar passive portfolio from scratch, then nominal bonds would be allocated a reduced role compared to the Slow & Steady, given what I know now.

I’d likely split the defensive allocation evenly between gold, commodities, short index-linked bonds, and nominal bonds.

If I rerun the historical tape from the end of 2010, that alternative Slow & Steady earns 8.2% annualised instead of 7.6%.

The difference isn’t huge. The portfolio is about 10% bigger. So it’s less about what could have been and more about what may come next.

A multi-layered defensive array is better fitted for the range of threats that menace passive investors. Not least the storm clouds of inflation and economic uncertainty.

This portfolio only has four years to run, so I should think about making those changes anyway.

New transactions

Every quarter we blow another £1,360 on the market dice and hope to roll sixes. Our stake is split between our seven funds, according to our predetermined asset allocation.

We rebalance using Larry Swedroe’s 5/25 rule. That hasn’t been activated this quarter, so the trades play out as follows:

Emerging market equities

iShares Emerging Markets Equity Index Fund D – OCF 0.18%

Fund identifier: GB00B84DY642

New purchase: £108.80

Buy 39.4804 units @ £2.76

Global property

iShares Environment & Low Carbon Tilt Real Estate Index Fund – OCF 0.18%

Fund identifier: GB00B5BFJG71

New purchase: £68

Buy 27.9077 units @ £2.44

Developed world ex-UK equities

Vanguard FTSE Developed World ex-UK Equity Index Fund – OCF 0.14%

Fund identifier: GB00B59G4Q73

New purchase: £503.20

Buy 0.5395 units @ £932.72

UK equity

Vanguard FTSE UK All-Share Index Trust – OCF 0.06%

Fund identifier: GB00B3X7QG63

New purchase: £68

Buy 0.1833 units @ £370.90

Global small cap equities

Vanguard Global Small-Cap Index Fund – OCF 0.29%

Fund identifier: IE00B3X1NT05

New purchase: £68

Buy 0.1188 units @ £572.42

UK gilts

Vanguard UK Government Bond Index – OCF 0.12%

Fund identifier: IE00B1S75374

New purchase: £285.60

Buy 2.1336 units @ £133.86

Global inflation-linked bonds

Royal London Short Duration Global Index-Linked Fund – OCF 0.27%

Fund identifier: GB00BD050F05

New purchase: £258.40

Buy 237.9374 units @ £1.09

New investment contribution = £1,360

Trading cost = £0

Average portfolio OCF = 0.17%

User manual

Take a look at our broker comparison table for your best investment account options.

Or learn more about choosing the cheapest stocks and shares ISA for your situation.

You might also enjoy a refresher on why we think most people are best choosing passive instead of active investing.

Take it steady,

The Accumulator
{ 45 comments }